A director lends her company £50,000 to cover a cash flow gap, and they agree to 5% interest a year. Nobody mentions HMRC, nobody mentions a CT61 form, and six months later the accountant asks whether anyone’s been withholding tax on those payments. Nobody has.
That scenario plays out in small UK companies constantly. The CT61 form covers Income Tax a company deducts before paying certain amounts to someone else most often interest on a director loan. It’s separate from your annual Corporation Tax return, and most companies never touch it. Where it does apply, it runs on a quarterly cycle with real deadlines, and director loan interest is where most first meet it.
What Is a CT61?
What Is CT61 Used For?
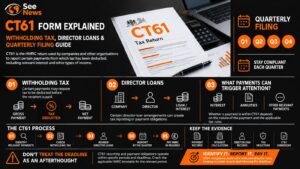
CT61 lets a company report and pay over Income Tax deducted from certain payments before those payments reach the recipient holding back a slice and sending it straight to HMRC. That’s the essence of CT61 form guidance: report what’s been deducted, then pay it over.
Which Payments Can Trigger CT61?
HMRC’s guidance lists interest (most commonly on a director loan), royalties, alternative finance payments, manufactured payments, relevant distributions in specific circumstances, and other similar regular payments. Most businesses only ever meet the first item. This falls under CT61 withholding tax rules.if yours goes beyond director loan interest, touching CT61 form distribution or CT61 form scrip dividends territory, check HMRC’s technical guidance first.
Is CT61 the Same as a Corporation Tax Return?
No. CT600 reports profits and calculates tax owed once a year; CT61 reports Income Tax deducted from payments made to someone else, on a quarterly cycle. A company can have a routine CT600 and still owe CT61 returns, or the reverse.
Does Your Company Need to File CT61?
When Does CT61 Apply?
CT61 becomes relevant the moment your company makes a payment where basic-rate deduction applies to direct loan interest being the classic trigger. The obligation follows the payment, not the company’s size.
Does Every Company Need to File CT61?
No. This is a common misread of CT61 form small companies guidance; plenty of owners hear “quarterly HMRC return” and assume it applies by default. If your company’s never paid interest to an individual, CT61 isn’t part of your calendar don’t file it speculatively.
Does Every Director Loan Require CT61?
Having a director loan on the books isn’t the same as owing a CT61 return. The obligation starts once the company pays or credits interest on it.This is where CT61 form director loans questions usually begin. A £100,000 interest-free loan creates no CT61 issue. Terms like CT61 director loan relief and CT61 form s419 relief relate to different rules around loans to which participants don’t treat them as CT61 reliefs.
What If There Is Nothing to Report?
Check bank transactions, the director loan account, and interest calculations before assuming nothing’s due. If HMRC has already requested a return, respond even if nothing’s owed.
How Does CT61 Withholding Tax Work?
What Does Withholding Tax Mean?
The payer deducts tax before the recipient sees the money, and the individual reconciles the position through Self Assessment.
What Is the CT61 Withholding Tax Rate?
HMRC’s guidance sets the CT61 withholding tax rate at the basic rate of Income Tax, currently 20% though the exact treatment still depends on the payment type and the recipient’s circumstances.
How Is the CT61 Calculation Worked Out?
- Gross interest: £5,000
- Tax deducted at 20%: £1,000
- Net payment: £4,000
The £5,000 is what’s earned, £1,000 goes to HMRC, and £4,000 lands in the recipient’s account. This CT61 form calculation repeats for every relevant payment all three figures need to appear on the return.
Who Pays the Withheld Tax to HMRC?
The company does. Once it deducts the tax, it’s responsible for paying that amount over via CT61.
CT61 and Director Loans
What Is a Director Loan?
A director loan account tracks money moving between a director and their company outside salary, dividends or expenses, a common source of CT61 form director loans questions. Either side can owe the other, and if the company owes the director and they agree to an interest rate, CT61 enters the picture.
What If the Company Pays Interest on the Director Loan?
The company withholds basic-rate tax before paying £5,000 gross becomes £4,000 net once the £1,000 deduction goes to HMRC. Getting this right depends on solid CT61 accounting treatment from the outset.
What If the Loan Is Interest-Free?
No interest, no CT61 obligation. Plenty of director loans run interest-free without triggering withholding tax, though other director loan rules can still apply.
What If Interest Is Credited but Not Paid?
This catches people out. HMRC’s rules apply to interest paid or credited, so the obligation can arise without cash moving, crediting £2,000 to a director’s loan account at year-end instead of paying it out still counts.
When Is CT61 Filed?
Why Is CT61 a Quarterly Return?
The tax needs collecting close to when the payment happens, not held over for annual reconciliation why CT61 form quarterly obligations exist at all.
What Are the CT61 Return Periods?
The standard CT61 form quarterly returns cover 1 January–31 March, 1 April–30 June, 1 July–30 September and 1 October–31 December the CT61 form period that each return maps to.
What Is the CT61 Due Date?
Tax deducted needs paying, and the return submitting, within 14 days of the quarter’s end. Miss that CT61 form deadline, or CT61 form due date, and interest starts accruing.
Does the Accounting Year-End Affect CT61?
Yes. If your accounting period doesn’t align with the standard quarters, you may need an extra CT61 return to cover the gap the reporting periods run independently of your Corporation Tax accounting period.
How Do You Complete and Submit CT61?
How Do You Get CT61 Online From HMRC?
You can’t download the form you requested, CT61 form online HMRC style, and HMRC posts it to your registered office. HMRC pulls that address from Companies House, so it’s worth confirming yours is verified before you request the form.
What Information Do You Need?
Relevant payments, gross amounts, tax deducted, payment or credit dates, recipient details, and supporting records that your CT61 form filing needs to be accurate.
How Do You Calculate the Amount to Report?
Work from gross to net for each payment in the quarter, applying 20% where it applies, and total the figures across all recipients.
How Do You Submit the Return?
Complete the physical form HMRC sends you and post it back this isn’t a fully online CT61 form submission. Keep a copy with your calculations.
How Do You Make the CT61 Payment?
Using the reference and payslip details on the notice, through the same channels as standard Corporation Tax.this is where the CT61 form payment gets settled.
CT61 vs Other UK Tax Forms
| Form / System | Main Purpose |
| CT61 | Tax deducted from certain company payments |
| CT600 | Corporation Tax return |
| CT600A | Certain loans to participators |
| P11D | Benefits in kind |
| PAYE | Employment-related deductions |
| Self Assessment | Individual tax reporting |
Why Are These Forms Often Confused?
They all report something to HMRC, so mix-ups happen easily, but each covers a different transaction filing CT600A correctly doesn’t excuse CT61, and clean PAYE compliance says nothing about a separate CT61 obligation on director loan interest. Good CT61 form compliance and sound CT61 accounting treatment mean knowing which form each transaction belongs to.
What If HMRC Asks for CT61 but You Have Nothing to Report?
HMRC often requests a return based on your company’s previous CT61 activity once you’re on their system, requests keep coming until you tell them otherwise. Check bank transactions, the director loan account, and previous returns before assuming nothing’s due, then respond either way, following CT61 form HMRC and CT61 form guidance processes. Ignoring it doesn’t remove the obligation and can trigger an estimated assessment. HMRC has tightened scrutiny of business tax claims generally, as our piece on R&D tax claim transparency shows, so ignored correspondence rarely goes unnoticed.
What If You Make a CT61 Mistake?
Paying interest without deducting tax, deducting the wrong amount, using the wrong quarter, or filing incorrect information all need reviewing promptly. Recalculate, contact HMRC where a CT61 form amended return is needed, and fix it as soon as you spot it part of good CT61 form compliance.
What Happens If CT61 Is Filed Late?
Are There CT61 Penalties?
A CT61 form penalty can apply for late or incorrect returns, though the outcome depends on the circumstances.
Can Interest Charges Apply?
Yes CT61 form interest charges can apply where HMRC charges interest on tax paid late.
What Should You Do If You Miss the Deadline?
Review the return, calculate what’s owed, submit or correct it, pay what’s due, and keep evidence.
Does CT61 Apply to Overseas Payments?
Paying interest or royalties to a CT61 form non-residents scenario can bring double tax treaties into play, and the effect varies by country and payment type. CT61 form relief may be available, but check the current position rather than assuming it applies.
CT61 Reliefs, Distributions and Other Specialist Situations
CT61 form relief on distributions sits within HMRC’s CT61 guidance, but the detail is specific enough to check directly. CT61 form scrip dividends don’t automatically create a CT61 obligation just because they’re a distribution. CT61 form s419 relief relates to the separate charge on loans to participants under CT600A, not CT61 keeping the two apart. CT61 form deferred payment situations follow the same “paid or credited” test: the accounting entry matters more than when cash moves.
What Records Should You Keep?
Payment records: dates, amounts, recipients, bank records. Director loan records: the loan account, interest calculations, supporting agreements. HMRC records: returns, payment confirmations, correspondence. Reconcile against your accounts each quarter as part of sound CT61 accounting treatment a gap surfaces eventually, and it’s better you catch it than HMRC does.
Common CT61 Mistakes to Avoid
Assuming every company needs to file, assuming every director loan triggers it, forgetting credited interest counts, confusing gross and net amounts, using the wrong period, confusing CT61 with CT600A, paying interest gross when tax should’ve been deducted, ignoring HMRC correspondence, relying on outdated guidance, and keeping incomplete records. Good CT61 form compliance comes down to catching these early.
CT61 Worked Example: Director Loan Interest
A director lends her company £100,000 at 5% annual interest £5,000 gross. This CT61 form example shows the mechanics: the company deducts £1,000 (20%), pays her £4,000 net, and reports it via CT61 within the 14-day deadline. She declares the full £5,000 on her Self Assessment return, and the £1,000 already deducted counts against her tax bill. Separate rules around loans to participants can also apply, replacing the CT61 obligation.
CT61 Quarterly Filing Checklist
Before filing: confirm CT61 applies, identify relevant payments, check dates, and calculate the gross and tax figures. Before submission: reconcile against your accounts, double-check the calculations, and review supporting records. After submission: keep a copy, keep payment evidence, and note the next reporting period all part of staying on top of CT61 form quarterly obligations and CT61 form filing.
Conclusion
CT61 form compliance isn’t something every UK company needs to think about, but for those paying interest, royalties or similar payments to individuals, it isn’t optional. The mechanics are straightforward: withhold 20% Income Tax, pay the net amount to the recipient, and report it within 14 days of the quarter’s end.
Director loan interest is where most companies first meet this form, and the “paid or credited” distinction is where most mistakes happen. Get the calculation right, use the correct quarter, and keep records that reconcile against your accounts CT61 then stays manageable quarterly admin rather than a source of penalties. Seenews will keep covering rules like this as HMRC’s guidance evolves, so you’re not left working from something out of date.