A community interest company CIC is a limited company built for community benefit, not private profit. Picture a founder running a community café that reinvests its surplus into local youth training; that’s the kind of venture this structure was built for. It works like a normal company, but with legal safeguards tying its assets and profits to that social mission.
Here’s the catch many founders miss: a CIC isn’t automatically a charity, and it isn’t tax-free. It pays Corporation Tax like any other company. This guide covers what a CIC is, how it works, what tax applies, and what setting one up involves. For more on UK business structures and compliance, see our guides section.
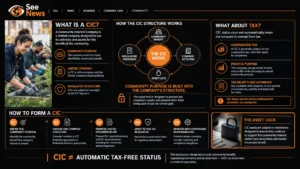
What Is a Community Interest Company?
What Does CIC Mean?
CIC stands for Community Interest Company, a limited company created under the Companies (Audit, Investigations and Community Enterprise) Act 2004, built for organisations trading for community benefit.
How Is a CIC Different From a Normal Limited Company?
Three things set it apart. It must state a community purpose in its constitution. It carries a statutory CIC asset lock, limiting how assets and profits can leave the company. And it files an extra annual report, which the CIC Regulator checks alongside standard company accounts.
What Can a CIC Do?
A CIC can trade, sell products and services, employ staff, sign contracts and own assets no different from an ordinary limited company. The real difference lies in what happens to the money it makes.
Examples of CICs
Common examples include:
- Community cafés and social kitchens
- Social care and support services
- Education and training providers
- Arts and cultural organisations
- Environmental and recycling projects
Each combines normal trading with a clear CIC social purpose and measurable CIC community benefit.
How Does a CIC Work?
Who Runs a CIC?
Directors run the company day to day, much like any limited company. Depending on the structure, there may also be members or shareholders holding formal governance rights.
Can a CIC Make a Profit?
Yes. A CIC can generate a genuine surplus; there’s no rule against making money. But the CIC surplus profit can’t be pulled out freely for private benefit; CIC profit distribution stays limited by the asset lock, and by the dividend cap where shares exist.
Can a CIC Employ People and Pay Directors?
Yes. A CIC can employ staff and pay directors a salary for real work they do. CIC directors responsibilities include keeping that pay reasonable, run through PAYE like any employment income.
Does a CIC Get Any Tax Benefits?
Does a CIC Pay Corporation Tax?
Yes, at the standard rate any UK limited company pays. Serving a community purpose doesn’t earn a discount.
Is a CIC Tax-Free If It Reinvests Its Profits?
No. This is one of the most common myths around CIC tax benefits. Reinvesting profit doesn’t create a tax exemption. HMRC treats a CIC as a company, full stop the CIC definition HMRC uses doesn’t carve out special relief for community-focused trading. For the underlying rules, our HMRC section is worth checking against your specific situation.
Does a CIC Pay VAT?
Yes, if it hits the normal VAT threshold, or chooses to register early. VAT rules apply exactly as they would to any other trading business.
Can a CIC Claim Gift Aid?
No. Gift Aid is a scheme for registered charities, and a CIC isn’t a charity, one of the clearest differences between the two structures.
What Tax Do CIC Directors Pay?
Director salaries go through PAYE, with Income Tax and National Insurance deducted as normal. Dividends, where paid, count as personal dividend income, subject to the CIC’s dividend cap. If you’re a director working out what a given salary actually leaves you with, our take-home pay calculator can help with the sums.
What Is the CIC Asset Lock?
What Does the Asset Lock Mean?
In plain terms, the CIC asset lock keeps the company’s assets and profits tied to its community purpose. It stops assets leaving below market value, unless they go to another asset-locked body.
Can a CIC Sell Its Assets?
Yes. The asset lock doesn’t stop a sale.it just requires the sale to happen at full market value, unless the buyer is another asset-locked organisation.
Can a Founder Take Money or Assets From a CIC?
A founder can draw a fair salary for genuine work, and claim back legitimate expenses. What they can’t do is quietly pull assets or profit out below market value for personal gain.
What Happens to Assets if a CIC Closes?
On dissolution, any assets left over must pass to another asset-locked body, not to shareholders or directors personally.
Can a CIC Receive Grants and Other Funding?
Can a CIC Apply for Grants?
Yes. Eligibility comes down to each funder’s own criteria, not CIC status alone.
Can a CIC Receive Donations?
Yes, but donations to a CIC don’t qualify for Gift Aid that relief is reserved for charitable giving.
Can a CIC Attract Investors?
A CIC limited by shares can issue shares and pay capped dividends, making it possible to bring in private investment while keeping most profit tied to the community purpose.
Does CIC Status Guarantee Funding?
No. Registering as a CIC signals genuine community intent, but doesn’t unlock funding on its own. A separate CIC interest cap also applies to performance-related loan interest, currently 20%, on top of the 35% dividend cap on distributable profits.
CIC vs Charity: What Is the Difference?
CIC vs charity comes up constantly. The two are genuinely different legal creatures.
| CIC | Charity | |
| Purpose | Community benefit | Charitable purposes |
| Regulator | CIC Regulator & Companies House | Charity Commission |
| Corporation Tax | Pays standard rate | Reliefs available |
| Gift Aid | Not available | Available |
| Trading | Freely, as core activity | Often restricted |
| Director pay | Reasonable salary allowed | Trustee pay restricted |
| Asset restrictions | Asset lock | Permanent charitable purpose |
When Might a CIC Be Suitable?
When founders want to trade commercially, keep flexibility over governance, and may want to pay themselves or investors within capped limits.
When Might a Charity Be More Suitable?
When the organisation wants charitable tax reliefs and Gift Aid, and is comfortable with stricter trustee and governance rules.
CIC vs CIO vs Limited Company
A CIO is a charity structure regulated solely by the Charity Commission, with charitable reliefs but no shareholder dividends. An ordinary limited company distributes profit freely and files standard accounts only. A CIC sits between the two: company law with the CIC Regulator layered on top, and capped dividends where structured with shares.
| CIC | CIO | Ordinary Limited Company | |
| Regulator | Companies House & CIC Regulator | Charity Commission only | Companies House only |
| Corporation Tax | Standard rate | Charitable reliefs available | Standard rate |
| Gift Aid | Not available | Available | Not available |
| Profit distribution | Capped dividends (if shares) | None no shareholders | Freely distributed |
| Asset lock | Yes, statutory | Yes, permanent charitable purpose | No |
| Annual reporting | Accounts + CIC34 report | Accounts + trustees’ annual report | Accounts only |
Which Structure Should You Consider?
A founder wanting full profit flexibility is better served by an ordinary company. One chasing charitable grants long-term may lean towards a charity or CIO. One trading commercially with a genuine community mission often finds the CIC the natural fit.
How Do You Set Up a CIC in the UK?
Here’s the practical route for how to set up a CIC, covering the core CIC formation requirements:
Step 1: Decide whether a CIC is suitable. Check the venture genuinely has a community purpose, and that CIC restrictions won’t clash with your plans for funding or profit.
Step 2: Choose limited by shares or limited by guarantee. A CIC limited by shares allows share issues, capped dividends and a defined CIC shareholding. A CIC limited by guarantee has no share capital and suits organisations without shareholder investors.
Step 3: Choose your directors. At least one is required by law.
Step 4: Prepare the community interest statement, setting out how the company will benefit the community, assessed against the CIC Regulator’s community interest test.
Step 5: Prepare the articles and CIC36. The CIC constitutional requirements include articles reflecting the asset lock, plus form CIC36.
Step 6: Register the CIC through Companies House, which forwards the application to the CIC regulator for approval.
Step 7: Set up accounting and tax processes Corporation Tax registration, bookkeeping, VAT if applicable, and payroll if you employ staff or pay directors.
How Much Does It Cost to Set Up a CIC?
Companies House charges a registration fee for incorporating a CIC, on top of the standard formation fee. Check the current amount on GOV.UK, since fees change over time.
Beyond registration, budget for:
- Professional or legal advice on the constitution
- Accounting and bookkeeping support
- Accounting software
- Payroll setup if employing staff
- Ongoing compliance costs
Weighing these against your wider budget is worth doing early. Our finance section covers broader money-planning topics that may help.
What Does a CIC Have to Do Every Year?
A CIC files annual accounts with Companies House, and must also submit the CIC annual report (form CIC34), explaining what it did to pursue its community purpose that year. It files a Corporation Tax return with HMRC as normal.
Ongoing CIC accounts requirements and CIC compliance mean keeping accurate records year round the CIC report and accounts rely on that groundwork. A dormant CIC still has filing obligations, though lighter than an active trading company.
How Many Directors Does a CIC Need?
One director is the legal minimum, the same as for a standard private limited company. Some funders like to see multiple, independent directors; that’s a funder preference about governance confidence, not a statutory CIC requirement.
Directors can be paid, as long as the pay reflects genuine work at a reasonable rate. Solid CIC governance means writing down how remuneration decisions get made and keeping that record transparent in the annual report.
Common CIC Mistakes and Misconceptions
A CIC is a charity. Different regulators, tax treatment and giving rules.
A CIC does not pay tax. It pays standard Corporation Tax, VAT and PAYE like any company.
A CIC cannot make a profit. It can the asset lock governs what happens to the surplus next.
CIC directors cannot be paid. They can, for real work, at a reasonable rate.
A CIC automatically gets grants. Funders assess each application on its own terms.
You always need two or three directors. The legal minimum is one; more reflects funder preference.
The asset lock means you cannot sell assets. You can, just at market value or to another asset-locked body.
Registration is the end of the process. Accounts, the CIC34 and governance carry on afterwards.
CIC status gives special tax relief. It doesn’t Corporation Tax apply as normal.
What Happens If You Change Your Mind About Being a CIC?
Converting out of CIC status is hard by design; the asset lock exists precisely to stop organisations shedding it for private gain once assets have built up. A CIC can convert to charitable status in defined circumstances, subject to Charity Commission and CIC Regulator rules. That’s different from a charity CIC transferring from charity into CIC form, which follows its own separate route.
On CIC dissolution, any assets left over must transfer to another asset-locked body, following the same lock that governed the company throughout its life.
Conclusion
A CIC is a limited-company structure built for community benefit, not a charity and not a tax-free vehicle. It can trade, employ staff and generate a genuine surplus, but the asset lock and profit restrictions keep that value tied to its purpose. Anyone weighing up the structure needs a clear view of formation requirements, annual compliance, and what the asset lock means in practice, before committing to it. For more plain-English breakdowns of UK business structures, Seenews is a good place to keep checking.